
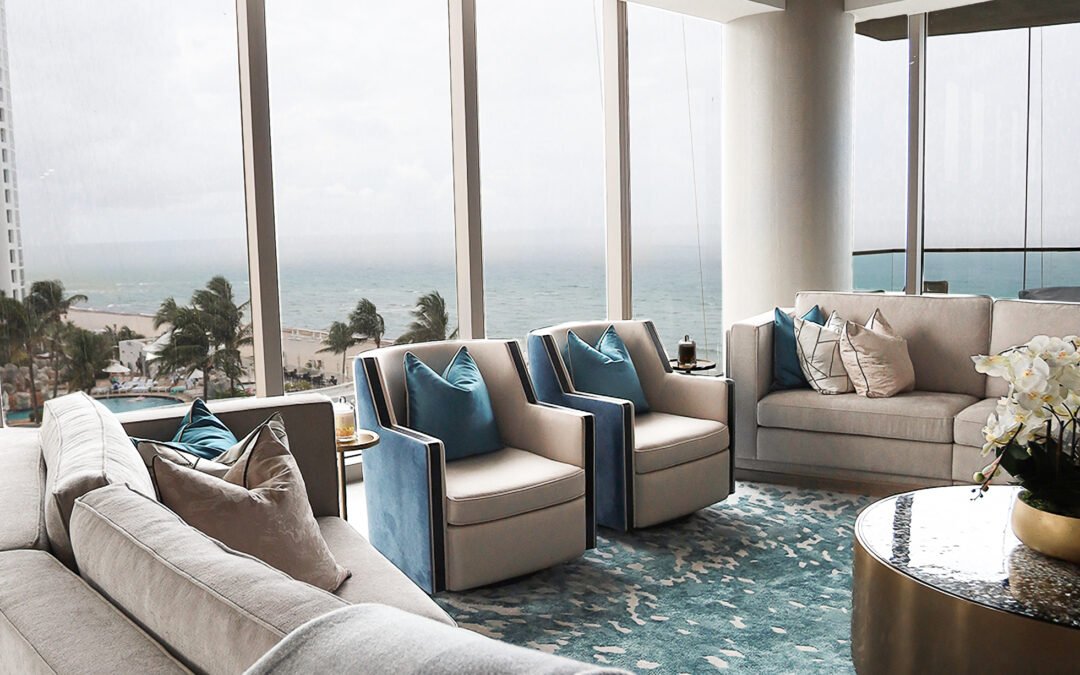
Few things define South Florida living like a view of the water. Waterfront homes and high-rise residences remain some of the most desirable properties in the region, but they also come with considerations that buyers in other markets rarely think about. Doing your homework on flood risk before you sign a contract can save significant money and stress down the road.
Understand the flood zone: FEMA flood maps classify properties into zones such as X, AE and VE, each with different risk levels and insurance implications. The zone affects whether flood insurance is required by a lender, what it costs, and how any future renovation or rebuild must be designed. You can look up a property’s zone on FEMA’s Flood Map Service Center before making an offer.
Ask for the elevation certificate: An elevation certificate shows how high the lowest floor sits relative to the expected flood level. It is one of the most important documents for pricing flood insurance and for planning renovations, and a favorable elevation can make a meaningful difference in long-term costs.
Get insurance quotes early: Flood insurance is separate from a standard homeowners policy. Compare options through the National Flood Insurance Program and private carriers during your inspection period, not after closing. Wind coverage, deductibles and the age of the roof and openings also play a major role in total insurance cost in Florida.
Review the property’s history: Ask about past flood claims, water intrusion and repairs, and review seller disclosures carefully. For condominiums, look at the association’s reserves, recent milestone inspection reports and any planned assessments, since building-level work can affect your costs as an owner.
Plan renovations with the rules in mind: In flood zones, substantial improvements to a property, generally those approaching half of the structure’s market value, can trigger requirements to bring the building up to current flood standards. Knowing this before you buy helps you budget realistically for the renovation you have in mind.
At Haus Signature, we regularly help clients evaluate waterfront properties before and after purchase, from assessing renovation potential to designing interiors that make the most of the view. If you are considering a waterfront home, we are glad to share what we have learned from years of working on these properties.
Flood maps, insurance requirements and disclosure rules change over time and vary by property. This article is general information only; please consult a licensed insurance agent, real estate attorney or local officials for advice specific to your situation.